TL;DR

Get office and shipping supplies delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Kiplinger describes options for people who cannot deposit an inheritance check through their bank’s mobile app, including contacting the bank, using a partner branch or asking the estate executor about an electronic transfer. After depositing the funds, the report recommends holding them in an insured, accessible account while making a plan. Bank policies, estate procedures and individual financial needs vary.
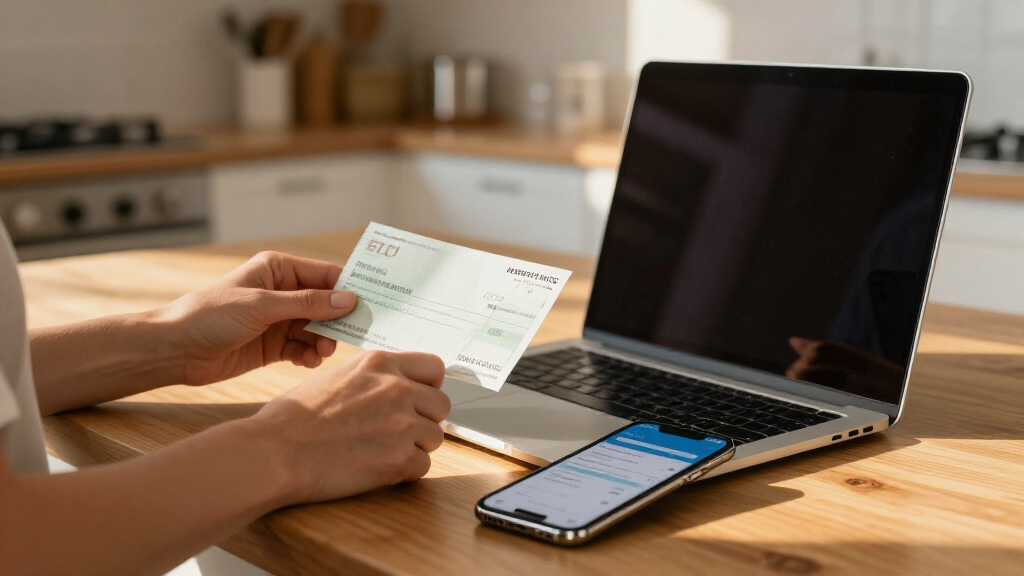
A Kiplinger report outlines options for people who receive an inheritance check but cannot deposit it through their bank’s mobile app, a potential problem for heirs who live far from a branch. The report says recipients can contact their bank about alternatives and, after depositing the money, keep it in a suitable account while they consider longer-term plans.
The report describes a colleague who received an inheritance check that was too large for mobile deposit and did not live near a branch of the bank. Kiplinger says the bank suggested sending the check by overnight delivery; it recommends using certified mail if mailing a check so the sender can track it and retain proof of delivery. The account is a personal example, not a universal description of bank rules.
Other possible routes include asking the bank whether it has a partner institution with a nearby location, or contacting the estate’s executor to ask whether the check can be canceled and the funds sent electronically. Kiplinger’s colleague said a brokerage firm arranged for someone to pick up the check, though the report presents that as an unusual solution that institutions may not offer.
After deposit, Kiplinger recommends setting aside time before making major decisions. It suggests considering a high-yield savings account, money market account or short-term certificate of deposit, while checking access rules and deposit insurance. Its report says eligible deposits at an FDIC-insured bank are protected up to $250,000 per depositor, per insured bank, subject to applicable ownership categories and rules. That limit does not mean every account or balance is automatically covered.
Getting the Check Into an Account
A large inheritance check can arrive during a period of grief, while the recipient may also be unfamiliar with handling a substantial sum. A deposit delay can add practical stress, especially for someone without a nearby branch. Contacting the bank before sending a check or arranging a replacement may help clarify acceptable methods, timing and any documentation the institution needs.
The next decision can carry financial consequences: where to hold the money, how much to keep accessible and whether to pay debt, save or invest. Kiplinger’s advice to pause and set goals is guidance, not a personalized recommendation. Account rates, withdrawal limits, fees, tax circumstances and the recipient’s needs differ, so the report does not establish one best choice for every heir.
For a person who has not managed a large sum before, the report also suggests speaking with a financial adviser or personal banker. It advises checking an adviser’s credentials, services, reputation and approach to client goals. Readers can ask how the adviser is paid and what duties apply before hiring anyone; the supplied material does not assess particular providers.
As an affiliate, we earn on qualifying purchases.
Why Mobile Deposits Can Be Limited
The report says some banks may not accept mobile deposits above a particular amount, and it describes a check exceeding $10,000 as a possible difficulty. That figure is presented as the situation encountered by the colleague, not as a statutory threshold or a limit shared by all banks. Deposit limits and procedures can vary by institution, account type and customer circumstances.
Kiplinger says banks may set limits using factors such as an account’s average daily balance and age, and suggests that recipients explain their situation directly to the bank. The report also notes that credit unions and other financial institutions may have partnerships that provide access to in-person transactions. These are possible arrangements; availability should be confirmed with the institution handling the deposit.
Holding the money temporarily in cash savings, a money market account or a short-term CD can give an heir time to consider goals. A CD may restrict access until maturity or impose an early-withdrawal penalty, while money market accounts may have transaction terms. The report mentions CDs of three to six months as one possible short-term option, not a guarantee of a particular return or a fit for every depositor.
““contact your bank directly to explain your situation.””
— Kiplinger report
As an affiliate, we earn on qualifying purchases.
Bank Rules and Estate Timing
The report does not identify the banks involved, their exact mobile-deposit limits or how long each proposed deposit method would take. It is also unclear whether an individual recipient’s bank will accept a mailed check, allow an exception, or work with a partner institution. Heirs should confirm the process, payee requirements, endorsement instructions and delivery address directly with the bank before sending an original check.
An electronic payment depends on the executor and the estate’s procedures. The report does not establish whether an executor can cancel and replace a check in every case, how quickly funds would be transferred, or whether the estate has completed all required steps. It also gives no details about the tax treatment of any particular inheritance; that can depend on the assets, jurisdiction and recipient’s circumstances.
The report’s account suggestions do not compare current rates or guarantee that a named type of account will preserve purchasing power. Rates and terms change, and FDIC protection applies under specific rules. The appropriate plan remains dependent on the recipient’s financial obligations, access needs and goals.
As an affiliate, we earn on qualifying purchases.
Confirm the Deposit Route First
Recipients facing a deposit problem can start by contacting the bank that issued or holds the receiving account and asking what options it accepts. If mailing is approved, confirm the address and required paperwork, use a trackable service, and keep copies of relevant documents. If the bank cannot accept the check remotely, ask whether a partner location or another approved method is available. Contact the executor before requesting a cancellation or electronic replacement.
Once the funds are available, review the account’s insurance coverage, fees, withdrawal access and terms before moving the money. A recipient considering a CD should check maturity and early-withdrawal conditions; anyone choosing a savings or money market account should confirm applicable limits and current rates. Those who want tailored advice can compare qualified advisers and ask about fees, services and fiduciary obligations. The next financial step should follow from the recipient’s own circumstances rather than the size of the check alone.
As an affiliate, we earn on qualifying purchases.
Key Questions
What should I do if my bank will not accept the inheritance check by mobile deposit?
Contact the bank and ask about its approved alternatives, including mailing instructions, a nearby partner institution or other deposit arrangements. Limits and procedures vary by institution.
Can I ask the executor to send the inheritance electronically instead?
You can ask the executor whether the check can be canceled and replaced with an electronic transfer. The estate’s procedures and circumstances determine whether that is possible and how long it may take.
Where can I keep the inheritance while I make a plan?
Kiplinger lists high-yield savings accounts, money market accounts and short-term CDs as options to consider. Compare access, fees, rates, terms and applicable deposit insurance; no single option suits every recipient.
Does FDIC insurance cover an entire inheritance?
FDIC coverage is generally up to $250,000 per depositor, per insured bank for eligible deposits, subject to ownership-category rules. Check how your accounts are titled and whether balances across accounts at the same bank affect coverage.
Should I hire a financial adviser after receiving an inheritance?
Kiplinger suggests considering an adviser if you want help planning. Check credentials, services, reputation, compensation and fiduciary responsibilities, and decide whether the cost and advice fit your needs.
Source: rss
Halloween Picks
halloween
As an affiliate, we earn on qualifying purchases.