TL;DR

Get office and shipping supplies delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
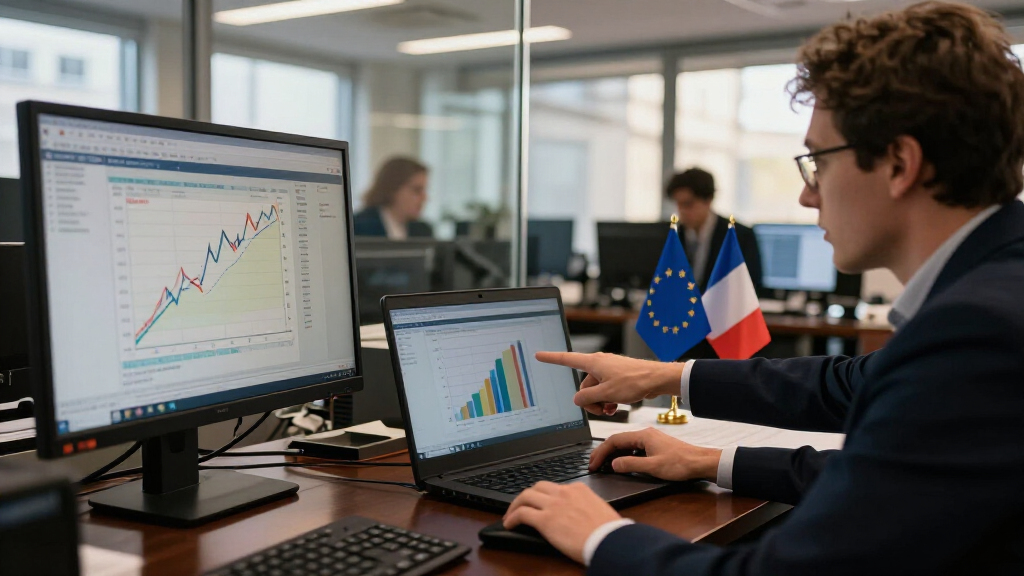
This Is Money columnist Alex Brummer warns that France’s difficulty addressing its budget and passing a 2027 budget could fuel wider bond-market and eurozone stress. The source reports French borrowing costs about 1.5 percentage points above German equivalents, but the scale of any further crisis and the ECB’s response remain uncertain.
French budget difficulties and political instability have prompted a warning that bond-market pressure could spread across the eurozone, according to Alex Brummer, a columnist for This Is Money. Brummer points to a reported 1.5-percentage-point gap between French and German government bond yields and argues that France’s struggles to pass a 2027 budget could test confidence in the euro, though a wider crisis is a risk he forecasts, not an established outcome.
The report says France’s government is struggling to pass a 2027 budget while confronting high public borrowing and rising debt-servicing costs. It states that, without deficit reduction, the annual deficit could reach 6.5% of national output and public debt 120% of GDP. Those figures are presented as conditional projections; the article does not provide the assumptions behind them or an official forecast source.
Brummer reports that French bond yields are about 1.5 percentage points above German Bund yields, describing the gap as the widest in 15 years. He also says the euro had fallen to a 17-month low of $1.12 against the US dollar. The report supplies no data date or market-data attribution for those figures, so they should be read as observations from the article rather than current live prices.
The columnist links the French situation to broader pressures, including weakness in Germany’s industrial economy, social unrest and uncertainty over European Central Bank leadership. He raises the possibility that ECB President Christine Lagarde could leave before her term ends, but provides no confirmation of such a plan. These points form part of his assessment of the risks, not confirmation that an institutional or currency crisis is underway.
How French borrowing affects the euro
France is a major eurozone economy, so a sustained rise in its borrowing costs could affect government finances and market confidence beyond the country. Higher yields can make refinancing more expensive and add to pressure on a government already trying to contain its deficit. If investors demand a larger premium to hold French debt, the widening gap with German Bunds may become a measure of concern about French fiscal risk.
The consequences would depend on whether market pressure persists and whether France can agree on credible budget measures. Brummer warns that a broader shock could affect the euro and global financial markets, but the supplied report does not establish that a crisis has spread or that global markets are facing an imminent downturn. His warning matters as a risk scenario; it should not be confused with a confirmed forecast shared by public institutions.
The report also discusses the ECB’s Transmission Protection Instrument, which allows purchases of government bonds in secondary markets under specified conditions. Brummer argues that using it to contain pressure could raise concerns about financing deficits and inflation. The source does not say that the ECB has activated the instrument or decided it would be appropriate. Its availability is relevant to how authorities might respond, but its use and effects remain hypothetical.
As an affiliate, we earn on qualifying purchases.
France’s budget dispute and bond spread
The report compares the present strain with the Greek fiscal emergency of 2009–10 and the wider bond-market tensions of 2010–12. That is Brummer’s historical comparison, not evidence that France faces the same conditions or that a crisis of equivalent scale has begun. France’s size and role in the eurozone make fiscal uncertainty consequential, while the source offers no detailed comparison of debt structures, policy responses or market conditions across the periods.
The article places the budget dispute amid other concerns: it describes Germany’s industrial machine as stalling, mentions riots in France and Spain, and notes speculation about Lagarde’s tenure. It also cites former Bank of England chief economist Andy Haldane warning that the UK is on “thin ice” unless it cuts public spending. These are contextual statements within the source, not direct evidence of a causal link to French bond yields.
Brummer’s report is an opinion column, and its central claim—that France could spark a major bond and euro crisis—is an interpretation of reported fiscal and market pressures. It should be distinguished from the underlying figures, which the source reports but does not independently document with linked official data.
““A Europe-wide crisis is a distinct possibility.””
— Alex Brummer, This Is Money columnist
Eurozone bond market analysis book
As an affiliate, we earn on qualifying purchases.
As an affiliate, we earn on qualifying purchases.
The scale of market risk remains unclear
The report does not state when its bond-yield and exchange-rate figures were recorded, identify the underlying market-data providers, or describe how long the spread had remained at the reported level. It also does not cite an official fiscal forecast supporting the conditional deficit and debt projections. Readers should not treat these numbers as verified current readings without checking dated market and government data.
It is also unclear whether France’s government can pass its 2027 budget, what spending or revenue measures might be included, or how investors would respond. The article provides no confirmation that the ECB is preparing to use its Transmission Protection Instrument, and its discussion of Lagarde possibly leaving early is speculation rather than an announced change. No evidence in the supplied material confirms that a eurozone-wide crisis or global market shock has begun.
As an affiliate, we earn on qualifying purchases.
Budget talks and market signals
The immediate test is whether France’s government can secure approval for a 2027 budget and set out measures to address borrowing. The source gives no timetable for a vote or details of a negotiated plan, so the next political milestone is not specified. Further developments in budget talks and official fiscal projections would help clarify whether the risks described by Brummer are easing or intensifying.
Investors and policymakers will also watch French bond yields relative to German Bunds, the euro’s exchange rate and any formal statements from the ECB. Those indicators could show whether market concerns are persisting, but movements alone would not prove that a wider crisis is inevitable. Any decision by the ECB to use its bond-market tools, or any confirmed change in the president’s tenure, would need to be reported separately from the speculation in this commentary.
As an affiliate, we earn on qualifying purchases.
Key Questions
What is the warning about France?
Alex Brummer argues that France’s budget difficulties and political instability could cause bond-market stress to spread across the eurozone. This is a risk warning in a commentary, not confirmation that such a crisis has begun.
What bond-market figure does the report cite?
The report says French bond yields were about 1.5 percentage points above German Bund yields, which it describes as the widest gap in 15 years. It does not give the observation date or name a data provider.
What does the report say about France’s deficit and debt?
It says that if the deficit is not reduced, it could reach 6.5% of national output and public debt could reach 120% of GDP. These are conditional figures reported by the column; the source does not provide the assumptions or an official forecast citation.
Has the ECB intervened in French bond markets?
The supplied report does not say that the ECB has intervened. It discusses the Transmission Protection Instrument as a possible tool and raises concerns about its potential use.
Is Christine Lagarde leaving the ECB early?
The article reports speculation about an early departure, while noting that her term was not due to end for another year at the time described. It provides no confirmation that she planned to leave early.
Source: rss
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.